Money you cannot spend: how Trust 2.0 carries out your wishes when illness takes over
Many people assume the biggest risk of old age is poverty. Walk into a hospital ward and you find the real one: the money is still sitting in the account, but illness or dementia has taken away the capacity to use it. When disease arrives without warning, how do you make sure your savings keep paying for your own care — and your family's?
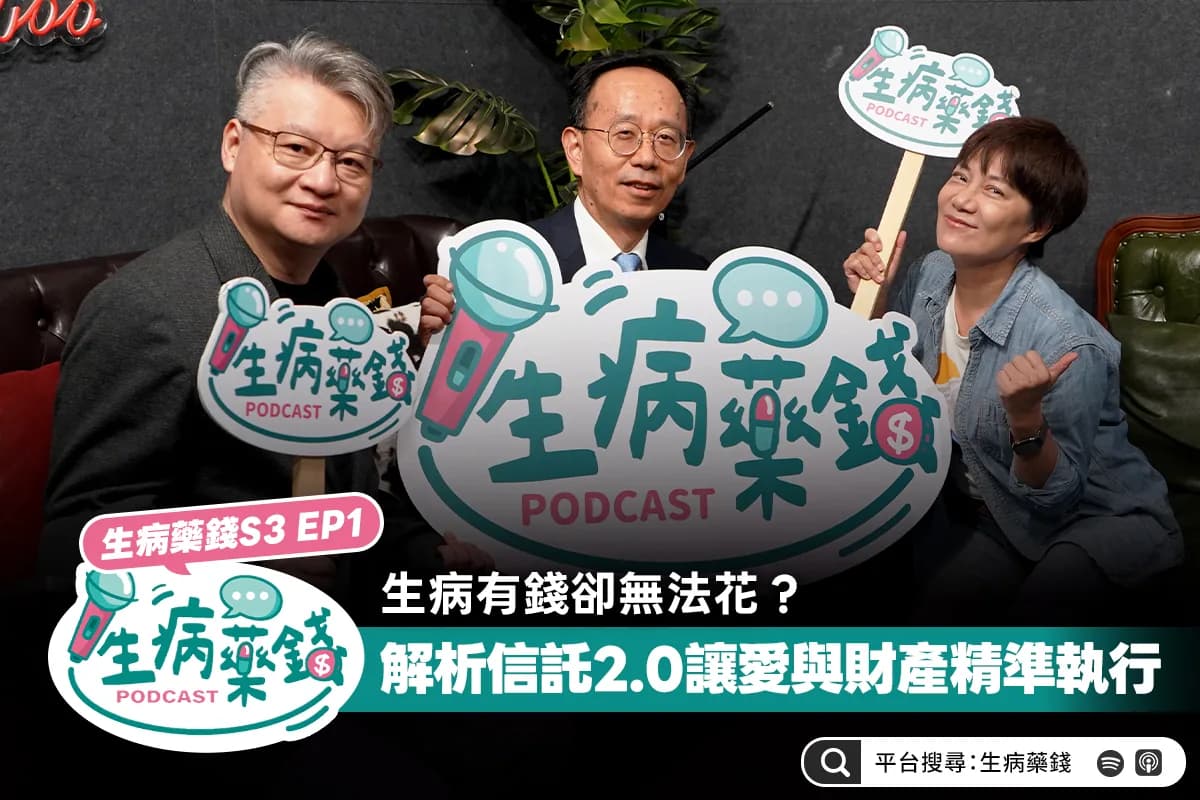
This episode of Sick Needs Money welcomes Tseng Wen-min, a manager in Hua Nan Bank's trust department, to explain how 'Trust 2.0' makes assets follow their owner's intentions, building a dependable safety net for later life.
What is Trust 2.0, and how does it differ from a bank account?
'Trust 1.0' was largely about investment or basic elder provision. As Taiwan becomes a super-aged society, the regulator's Trust 2.0 framework brings insurers, healthcare providers, social welfare bodies and lawyers together into a fuller plan for later life.
People often ask: if the money in my bank account is available any time, why bother with a trust? The difference lies in transfer of title and earmarked use:
- Ownership: a deposit belongs to you personally and is exposed to fraud or misappropriation; a care trust moves title into a bank trust account held for you.
- Flexibility: a deposit can be withdrawn at will, but no one can withdraw on your behalf once capacity is lost; a trust account disburses under the contract, which is what gives it protective force.
- Purpose: deposits are for saving and everyday payments; a trust is for guarding against fraud and directing both care and succession.
What a trust can actually do: three situations
Trust contracts are highly customisable:
- Providing for children with a spendthrift brake: a monthly living allowance, with start-up capital or a marriage fund released only when the conditions in the contract are met.
- Combining voluntary guardianship with a trust supervisor: if you fear future incapacity, name a trusted relative, a lawyer or a welfare organisation as trust supervisor to make sure medical bills get paid.
- 'Trust Pay' with no paperwork: linked to hospital payment systems, registration and treatment fees are debited from the trust account directly, with no receipts to file manually.
Insurance proceeds trusts: keeping a payout out of the wrong hands
People buy death benefits and maturity benefits to provide for the next generation. But when the beneficiary is young or inexperienced with money, a large payout attracts attention.
With an insurance proceeds trust, the policyholder signs the trust contract and then asks the insurer to endorse the policy. When the benefit is paid, it goes straight into the bank trust account and is released as a monthly allowance — which is what the policy was for in the first place.
The sequence: sign the trust contract → the insurer endorses the policy → the benefit lands in the trust account → the bank disburses on schedule.
Within reach: the pre-opened trust
Trusts are not only for the wealthy:
- Fees are modest: account opening costs roughly NT$500–1,000 (some banks discount it for people with disabilities or charitable donors), and annual management fees run about 0.2%–0.5% of assets — sometimes covered by the interest on a time deposit alone.
- Pre-opened trusts: sign the contract while you are healthy, and pay no management fee until money is transferred in — preparation made in advance of the risk.
Insurance answers whether the money exists. A trust answers whether it can be spent the way you intended. Planning a care trust early is a reassurance worth giving yourself and your family.
Sick Needs Money unpacks the real problems that begin after diagnosis, every week.