Using policy value to bridge a crisis — and bringing an old policy up to date
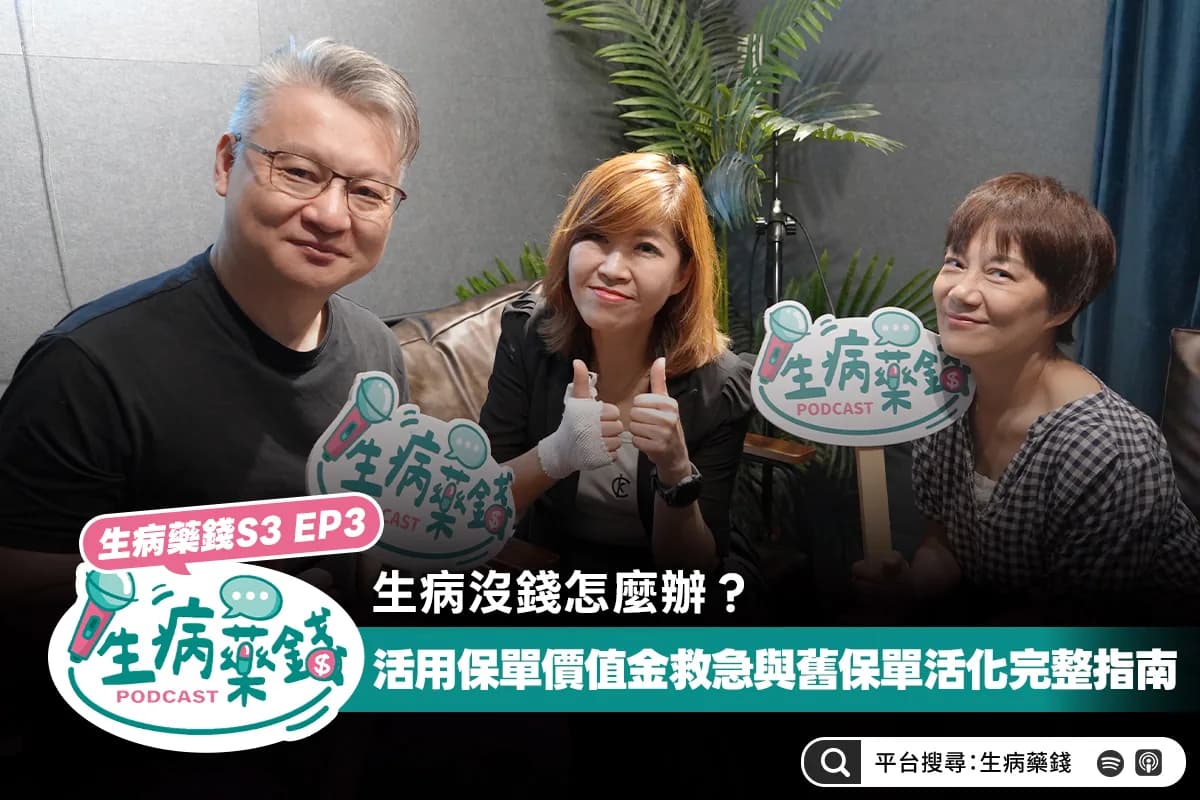
Facing a large medical bill with not enough cash on hand — what then? Most people assume insurance only pays out after an event, but an asset-type policy is also an important source of liquidity.
Ting Hsiao-ling, an associate vice president at Everpro Insurance Brokers, explains that understanding policy value correctly, and restructuring rather than surrendering, buys you more medical choice and more financial flexibility.
Short-term relief: the value inside an asset-type policy
Insurance divides broadly into protection products (medical, accident, disability) and asset products (interest-sensitive, participating, investment-linked). The policy value reserve — the surrender value — that an asset policy accumulates can be borrowed against in an emergency:
- Interest accrues daily: the loan rate is typically the policy's assumed rate plus 1%–1.5%, borrowed and repaid at will.
- No credit check: no income documentation, no bank credit assessment, and you decide what the money is for.
- Borrowing limits: NT-dollar policies typically allow 80%–90% of the policy value; foreign-currency policies around 70%.
Managing the risk: avoiding lapse
Policy loans are convenient, but if principal and interest are not serviced and the accumulated debt exceeds the policy value reserve, the policy risks lapsing. Should a medical event occur while the policy is lapsed, the insurer is not liable.
- Check the automatic premium advance: confirm at application whether you consented to premiums being advanced from the policy value, which prevents a missed payment from causing an immediate lapse.
- Reinstatement: a lapsed policy can be reinstated within two years. Within the first six months the process is simple — a health declaration. Beyond six months a fresh medical examination may be required.
- Consider a double waiver: check whether the policy waives premiums. A single waiver stops future premiums on critical illness or disability; a double waiver adds a cash supplement on top, transferring the risk of interrupted income.
Keeping up with medicine: three ways to refresh an old policy
As technique improves, hospital stays shorten and more surgery moves to outpatient settings, so a policy bought years ago may no longer fit. You do not have to surrender it:
- Restructure the riders: think of a policy as a train — the main contract is the locomotive, riders are the carriages. Where an old rider no longer fits, reduce the daily-benefit medical cover under the same main contract and add or raise outpatient surgery and reimbursement cover.
- Fill the senior gap: traditional reimbursement cover often stops between 65 and 75. Consider adding whole-life reimbursement cover that activates after 75.
- Use reduced paid-up or extended term: under prolonged financial pressure, convert to reduced paid-up (lower sum insured, same term) or extended term (same sum insured, shorter term) to stop paying main-contract premiums while keeping the riders in force.
The long view: substantive taxation and beneficiaries
A policy is part of your asset allocation, and deserves a periodic review as life changes:
- Watch the substance-over-form taxation principle: where an asset policy's surrender value far exceeds the death benefit, the payout may be treated as a taxable asset. Tax rules move, so keep track.
- Keep beneficiaries current: update the order of beneficiaries when marriage or family structure changes, and add 'statutory heirs' at the end to avoid disputes.
- Use the insurance passbook: the Life Insurance Association of the R.O.C. runs a free platform where you can look up every policy in your name, active and lapsed, and see what you actually hold.
Prevention beats treatment. Review the structure of your policies and build an emergency fund while you are healthy — that is what lets insurance genuinely back you up, medically and financially, when risk arrives.
Sick Needs Money unpacks the real problems that begin after diagnosis, every week.